SOLAR LEADING THE WAY

Each week new records are broken across the energy market. Be it historic record low demands, reducing levels of thermal plant availability or the increased availability from renewables.

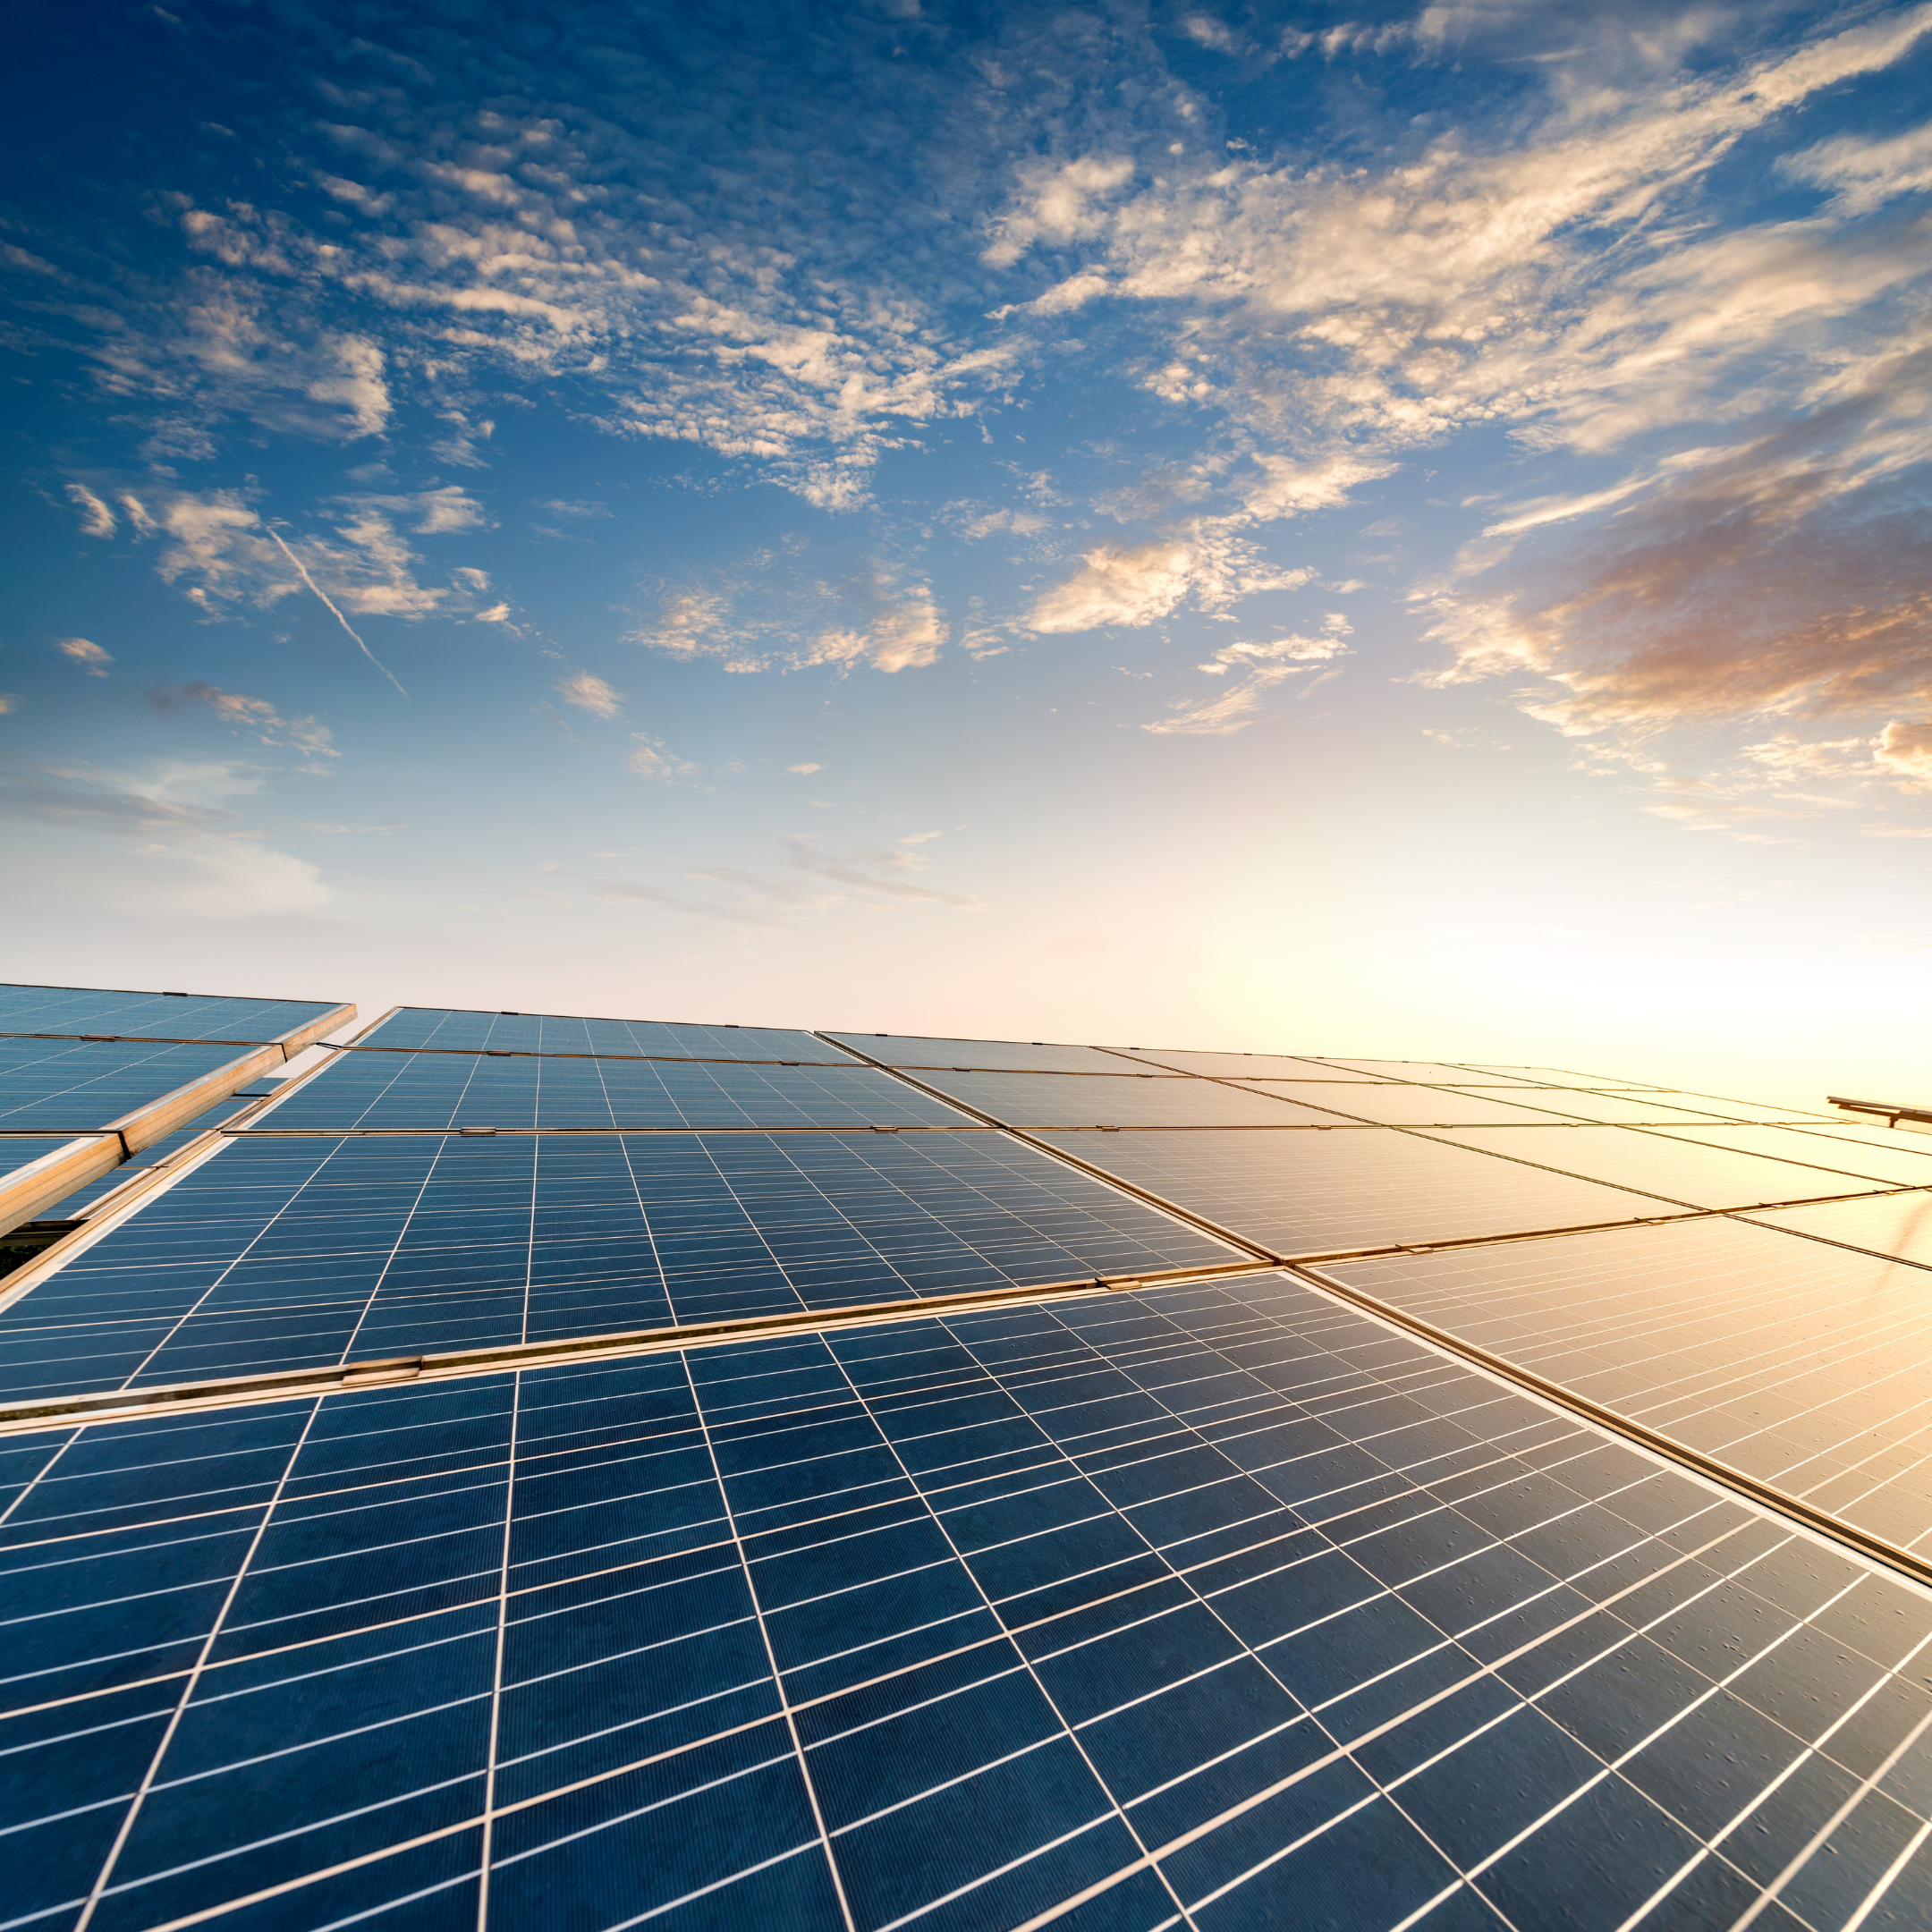
Last week saw solar reach more than 50% of Australia’s demand. This came as record generation levels came from both rooftop PV and large-scale solar sectors.

Ironically this record occurred on Sunday while the National Party room was meeting to discuss their stance on net zero emissions. As the Nationals push to lift the profile of the coal industry and power the country from coal fired power stations, solar generation reached 51.8% of the NEMs demand.

While regions like South Australia have passed the 50% solar milestone during the weekend it was the first time the NEM reached more than 50%. As expected, solar provided most of the electricity between 11:00 and 13:00, peaking at 11:55.

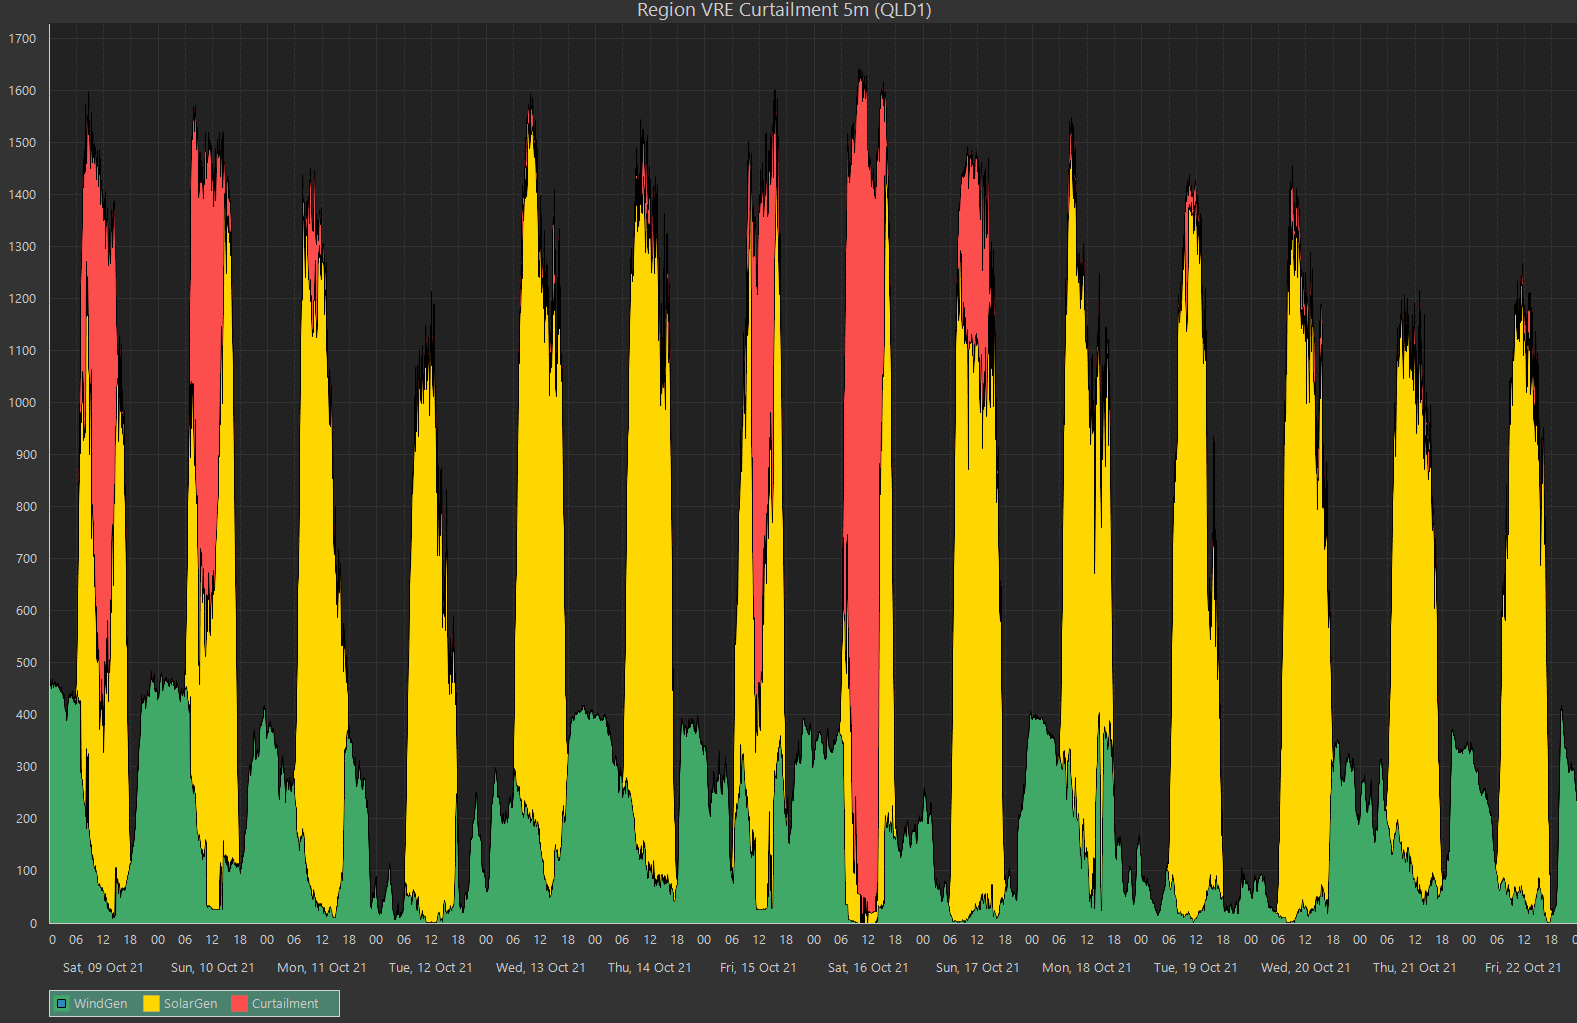
The 50% hurdle could have been higher as negative prices in South Australia economically constrained some large-scale solar plants. On the previous day, the record would have been broken if not for Queensland economically constraining off 1,800MW of large scale solar due to negative prices.

As mentioned above the NEM is also experiencing low operational demands and in line with the high rooftop PV generation, the demand dropped to a record low across the NEM of 12,936MW on Sunday as solar reached over 50% generation. As rooftop PV is not economically constrained, it accounted for 38% of the underlying demand.

As solar generation increased, it displaced coal fired generation with black coal generation throughout Queensland and NSW reaching historic lows of 6,105MW.

These statistics were surely discussed in the Nationals party room over the weekend and along with AEMOs forecasts showing the NEM can reach 100% renewables by 2025 as their base case scenario in modelling such as the ISP and the ESOO, the question about the role of renewable and coal in the market must have been discussed.

During the Spring months, skies are clearer and air temperatures are conducive to low air conditioning and heating loads, we could realistically see a situation where rooftop PV could cover demand. Of course, this will cause issues for AEMO who are required to keep various synchronous units online for system security however recent changes have allowed AEMO to employ systems to switch off solar in the event of a grid event to maintain grid security.

Written by Alex Driscoll Senior Manager Markets, Trading & Advisory

Summer Weather Outlook

The Australian Bureau of Meteorology (BOM) has officially put La Nina on a watch status for the second year running. This means there is around a 50% chance (double the normal chance) of the phenomenon re-forming in 2021.

This is seconded by the US National Oceanic and Atmospheric Administration (NOAA) climate prediction centre forecasting a 70% chance of La Nina forming for the second consecutive year.

The Summer and Autumn of 2020 – 2021 were the wettest and coolest experienced in Australia for the past 5 years, and this was driven by the La Nina effect. Although not as extreme as the 2011 La Nina event, which was one of the strongest la Nina’s seen on record, we would expect that if it does form again this year it would most likely follow last year’s pattern.

There are other drivers looking to encourage a wet summer as well.

The lesser known Indian Ocean Dipole (IOD) is the temperature difference between the Eastern and Western Indian oceans. A positive phase of the IOD would lead to less rainfall and a negative IOD leads to more rainfall in the South and East of Australia throughout Spring.

In 1974 a negative IOD occurred with a strong La Nina and Australia recorded the wettest year on record. Although the two can coincide it is a complicated relationship and a significant area of research within the Climate community.

This year the latest BOM outlook has 3 of the 5 international climate models moving the IOD negative from October. Although not sustained into 2022 and a weaker index than some previous years, a negative IOD would still be expected to increase the chance of a wet Spring. The weakening of the index into the Summer is a standard trajectory for the IOD.

On the other side of the continent, the Southern Annular Mode (SAM) (related to the Antarctic Oscillation (AAO)) is showing a slight positive indicator. This correlates with a strengthening La Nina index as the two tend to be more correlated than other indices. A positive SAM will lead to more rainfall in the East and reduces the chance of a hot Spring and Summer.  Although as per the La Nina index these are not strong signals and could therefore change going into the later Summer and are mainly Spring indicators at the moment.

A final influence could come from the Madden-Julian Oscillation; however, these can only reliably be forecasted 14 days in advance as they pass around the planet every 30 to 60 days. If one forms you can expect North-Eastern Australia to experience significant rainfall as the system passed into the Pacific. They can bring monsoons and tropical Cyclones if occurring in the Spring and Summer and if this forms at a period of heavy rainfall we can expect it will significantly increase the flooding risks from the ground which is already saturated.

So, what does that do to our Summer? Well for us on the Eastern Coast it means don’t put away the gumboots and rain mac just yet. It is likely to be a rather wet Spring and depending on the development of some systems it could go all the way through our Summer. It also means we can expect the Spring to have cooler days across Eastern and Southern Australia and increased cloud cover leading to milder evenings.

From a generation point of view, increased cloud cover could lead to reduced Solar capacity for both large scale and roof-top systems and this will likely be coupled with below average winds in the Southern NEM.  There is a winner though, the Hydro plants in NSW and Victoria will be happy campers, if not a little sodden, with a higher than average rainfall expected in those catchments this Spring.

Article Written by Kate Turner Senior Manager Markets, Analytics & Sustainability

BASELOAD COAL GENERATION LOSING THE BATTLE

Since the release of the latest Electricity Statement of Opportunities (ESOO), Edge has updated its energy price forecast and the energy landscape is looking difficult for the remaining baseload coal generators. Most of the coal-fired generators remain in vertically integrated portfolios which used to use the cheap coal generation to subsidise the more expensive gas and renewable generation. With the increased penetration of renewables, the cost for these assets has reduced and become a burden on the portfolio. With the cost to maintain the thermal units to meet reliability standards and generating less, the cost per MWh is increasing.

The change in the market is reducing the value of what non-renewable generation has on portfolios. Companies with large coal exposures have written down their coal assets and needed to change their business model to survive.

Renewables are pushing out coal-fired power stations and putting increased pressure on the gas-fired generators. Over the last decade, renewable energy has been gaining market share and with reducing installation costs, the share of the market has increased over the last 5 years. In the last 2 years, renewables have generated more electricity than brown coal following the closure of Northern Power Station in South Australia and Hazelwood in Victoria.

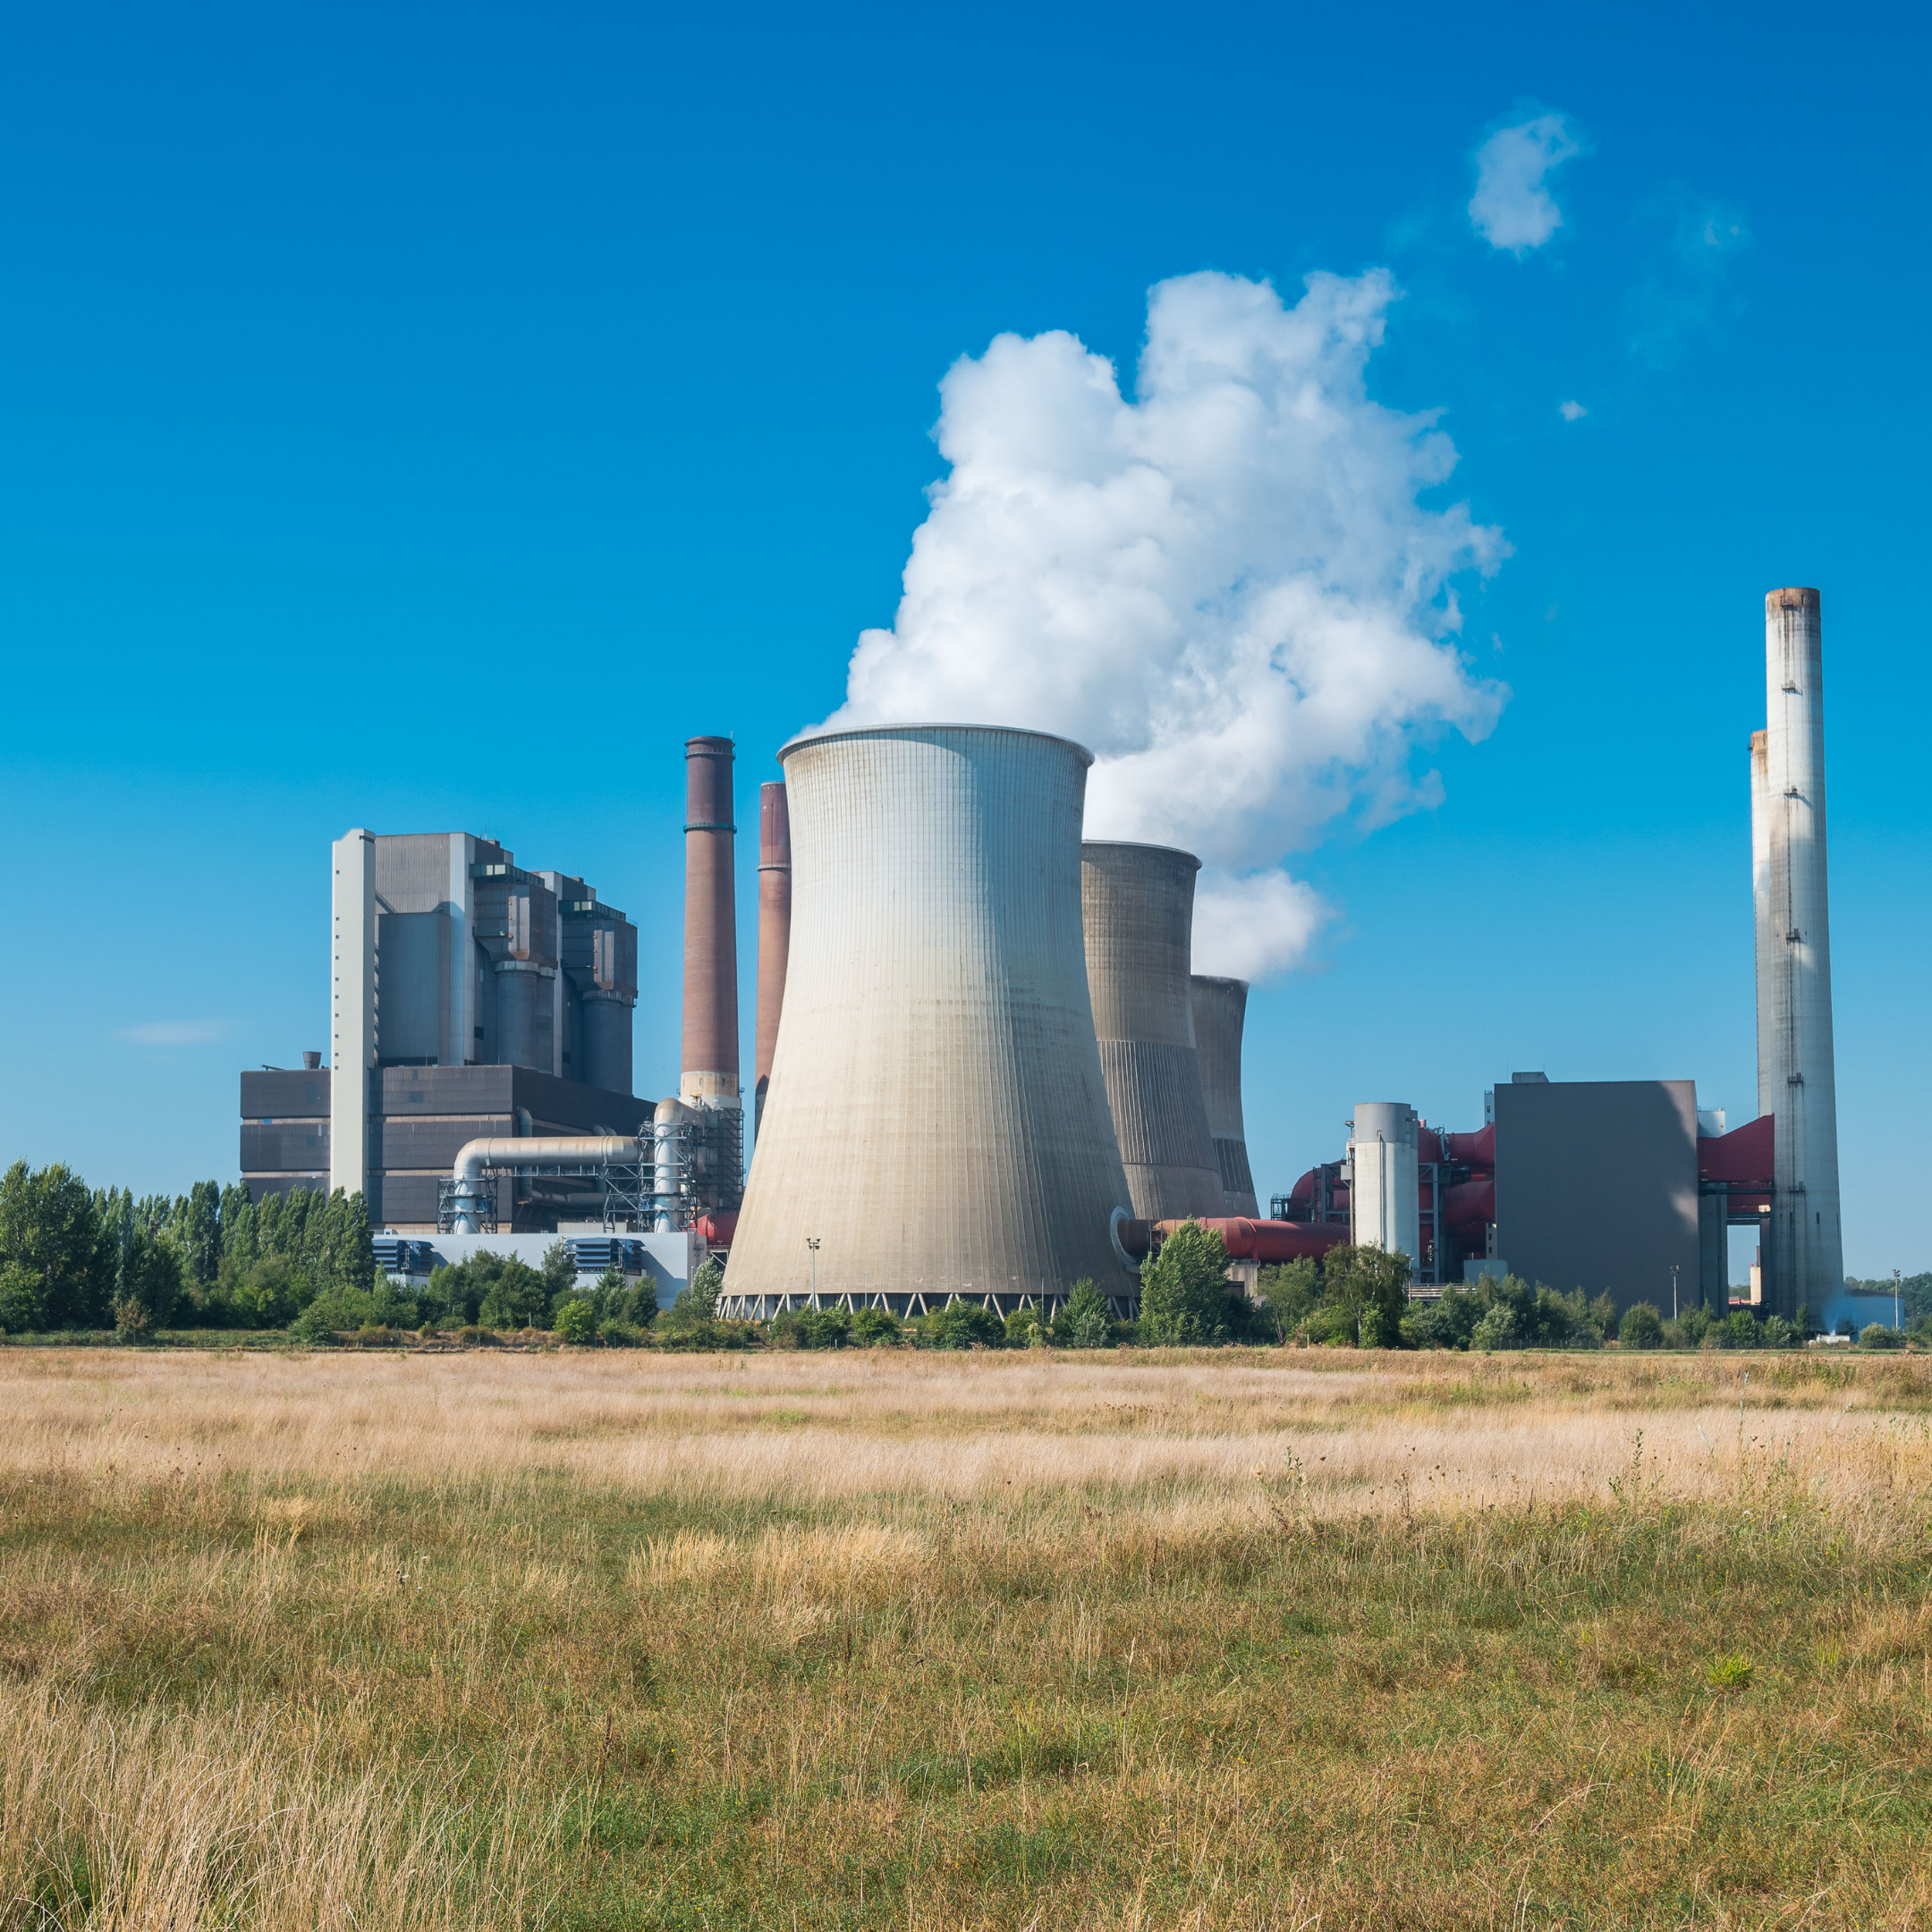
Black Coal Power Stations are next to be impacted by renewables. Although until recently the biggest threat has been for Solar during daylight hours, which still allows the thermal generators to make their required returns outside solar hours. This equation is changing with the increased penetration of batteries that will increasingly allow solar generation to be time-shifted into non-daylight hours and hence reducing the number of hours thermal generation can control spot prices.
With Solar, we are seeing a marginal cost of generation of $0/MWh so these power stations bid into the market at $0/MWh which pushes more expensive generation further up the bid stack. When negative spot prices occur, increasingly we are seeing large scale solar generation curtailing their generation to reduce their exposure to negative prices. Due to the nature of Solar generation which can increase or decrease their generation very quickly, this practice is causing issues for the market operator.

The energy market is cyclic, we have seen high prices which lead to investment in generation followed by low prices as demand grows to meet the extra generation. Between 2017 and 2020 we had record-high prices across the NEM following the closure of Hazelwood. We are now experiencing record low prices because of the influx of cheap renewable generation. These low prices are putting pressure on the financial modelling of future renewables, which has the potential to impact the supply and demand balance in the future once the aging coal-fired fleet retires.

Capacity factor, the ratio of actual electricity output to the maximum electricity production from that specific asset, is falling for all coal-fired generators. The next coal-fired power station to close has dropped in capacity to 42% and other aging power stations have also dropped well below 70%.

The first state to have no coal-fired generation is South Australia and this state has been working through the challenges of a market filled with intermittent generation. The market operator has worked to resolve the technical issues arising from high penetration of intermittent generation, these solutions are starting to be used across the NEM.

South Australia at this moment in time is where we will see the other states in future years. System stability is becoming the issue and finding solutions to provide inertia which is key to system stability.

Another issue for the market is when the intermittent generation does not generate the demand that needs to be met for more expensive dispatchable generation such as fast responding gas turbines.

The problem for the market is not the increased penetration of renewable energy or system security, it is who and what fill the supply gap once intermittent generation is taken out of the equation. At times this residual amount can be very high.

The reserve can be filled by coal or gas, but the baseload units are not designed to only operate on the part of the days when they are required. Currently, these units stay online 24hrs per day. The only option they have is to reduce their output to minimum load to reduce output and potential losses resulting from very low prices.

As the coal plants become older and less reliable the service, they provide becomes less dependable, so more reliable solutions such as gas-fired generation or batteries once they become commercially viable are the solution. This leaves coal-fired generators in a market that they can’t sustain their required returns and can’t provide the service with the market needs due to their lack of flexibility.

As the growth in renewable increases, coal will be pushed out as the financial pressure on the generators and retailers increases. Retailers will renew their fleet of assets to meet the future need of their business and reducing maintenance costs and reducing emission liabilities will be the key driver to retiring the coal fleet. Coal-fired power stations are struggling to make the required returns now with most stations unable to remain viable after 2030 if the current price trend continues.

The government may have thrown the coal-fired generators a lifeline with the Energy Security Board (ESB) capacity market post-2025, where generators will be paid to remain available to provide inertia and other system security services. The issue with the lifeline is in the future. There will be other technologies that will be able to provide these services at low prices, making coal-fired generators obsolete.
Things to check when procuring a new energy contract

Brokers and Consultants play valuable roles in assisting you to go to market to review your energy costs and your needs. They can help you to efficiently review several energy retailer offers.

This Guidance Note has been created by the National Customer Code for Energy Brokers, Consultants and Retailers. It aims to help you navigate your energy procurement to ensure that you are making informed decisions about costs, commissions and fee structures, including any ongoing fees and terms. You’ll also find some practical questions to ask your broker or consultant if you need more information.

https://www.theenergycharter.com.au/wp-content/uploads/2021/10/Energy-Charter-Broker-Procurement-Checklist-Final-Oct-2021.pdf

NEW TOOLS FOR AEMO

We all agree having a safe, reliable, and secure National Electricity Market (NEM) is the key deliverable for AEMO. AEMO have flagged that there is a shortfall in the participants able to provide key services to keep the grid stable as the generation mix changes and they are running out of tools to keep the grid stable.

The biggest issue for AEMO and market participants is as synchronous generators such as thermal power stations reduce availability and eventually retire the much-needed system security services such as inertia and voltage control that they provide, drops.

As a result of AEMOs concerns, the Australian Energy Market Commission (AEMC) has developed ways of valuing the much-needed services.

The AEMC has just released a directions paper outlining mechanisms that could provide the system security services to the NEM. The AEMC has also highlighted support for innovative technologies to provide these services.

At this moment in time, AEMO has limited tools to improve system security at times of scarcity apart from using its intervention powers to direct generators online to provide the services. The problem with using its direction powers is that additional costs associated with the directions are passed onto end users and as a result this does not meet the requirement of the National Electricity Objective (NEO) of providing the lowest cost solution and it also distorts the market.

AEMC’s directions paper covers two rule changes proposed by Delta Electricity and Hydro Tasmania. The Delta proposal is to introduce a capacity commitment mechanism to provide system security and reliability services. In Hydro Tasmania’s request they propose to create a market for inertia, voltage control and system strength products.

Both these rule changes will form part of the Energy Security Boards (ESB) ‘post 2025’ market design. AEMO is also working with participants to develop the engineering to meet these challenges. These challenges include a changing market due to an increased reliance on weather dependent generation such as solar and wind and new technologies such as batteries.

The options in the directions paper are about providing a transitional approach as we move to a different generation mix while keeping the cost of the solutions to a minimum over the long-term. Solutions may include a similar process to direction but increasing the transparency of what assets should be online to maintain system security while keeping the costs down. Some of the options available to AEMO could be scheduling assets to provide specific services like voltage control while other would be scheduled for inertia. These arrangements would likely transform into stand-alone services similar to the current FCAS services.

The market is changing at a rapid pace and these extra tools in AEMO’s toolbox should allow the NEM to operate safely and securely for many years into the future.

SNOWY 2.0

With the release of the latest Electricity Statement of Opportunities (ESOO) some of the assumptions used in it have raised concerns of the viability of Snowy 2.0 and the impact it will have on security of supply for the market. Snowy 2.0 had been given the green light under AEMO assumptions even though the project would not have hit the hurdle rate AEMO uses for all other projects.  The second concerning point is when you build one of the largest generation assets in the country it is crucial that it is linked to the market via appropriate transmission lines. Information from transmission line providers suggests the full capacity of the powerlines will not be in place when Snowy 2.0 comes online. Our third concern is the cost of the new transmission line projects are rapidly rising. These costs will go directly to the end user.

Transmission provider TransGrid outlines information on HumeLink, the transmission line earmarked to connect Snowy 2.0 to the NEM. TransGrid estimates HumeLink costs have increased from $1.3B in the draft assessment to $3.3B. The more worrying statement is TransGrid saying the final cost could be up 50% or more.

Apart from HumeLink, to be full unconstrained, Snowy 2.0 will need the Victoria to NSW interconnector West (VNI West) transmission to be built. HumeLink is labelled the largest transmission project in history, VNI will be a similar size and most likely a similar price however costing have not been released.

The cost of these two transmission lines will eventually be passed down to end users via increases in transmission tariffs. Modelling has indicated that the $3.3B for HumeLink will add 40% to NSW costs. While these costs are met by all end users, large users will be impacted the most as these fees are paid for on a proportional basis.

Latest costing suggests HumeLink, VNI West and Snowy 2.0 has the potential to cost $12 billion. This will make Snowy 2.0 the most expensive generation and transmission project in history.

The question is, with far cheaper renewable projects that do not require 2 huge transmission lines to make them effective for system security, are there better options the federal government and the consumers of NSW could be spending their money on.

SOLAR SLOWING DOWN

Recent data shows there is a slowdown in the rooftop solar industry, and this is likely to continue as prices rise. Installations in August dropped, most likely due to the current lockdowns in NSW and Queensland. NSW installations have been the heaviest impacted followed by Victoria then the largely COVID free Queensland.

The early growth in the roof top PV market has gradually reduced with 2021 largely being flat across Queensland and Victoria. Early adopter states like South Australia are gradually declining due to early adopters reaching capacity. The growth in the early adopter segment is now replacement of existing systems with larger systems.

It is likely that the continued growth in states like Queensland are a result of COVID related home improvement plans funded by government financial stimulus.

Recent talk of a ‘sun tax’ has prompted people to install roof top PV before the changes occur while residents in SA would be concerned about installing a system that can be switched off when system conditions occur potentially leaving them exposed to high electricity cost. The other driver slowing the uptake of roof top PV is the lower feed in tariffs offered by retailers. The lower feed in tariffs do not make the installation of roof top PV as attractive and large-scale renewable energy should also bring down the retail cost of electricity.

With recent changes to the exchange rate the cost of imported panels will increase and as a result roof top installation will become more expensive. Higher installation costs and lower feed in tariff reduces the incentive for households to install solar.

As the number of installations drops, operational demand is less impacted during solar hours as consumption increases over time. Under the small-scale renewable energy scheme, liable entities are required to surrender the number of small-scale technology certificates (STCs) equal to that produced each year so as the number of certificates created each year increases the number of certificates they need to procure also increase. Any slowdown in the installation market may even reduce the percentage of certificates the liable entities need to surrender. STCs are likely to stay in their narrow trading range even if the number of certificates created each year fluctuates.

NEW RENEWABLES ON THE HORIZON

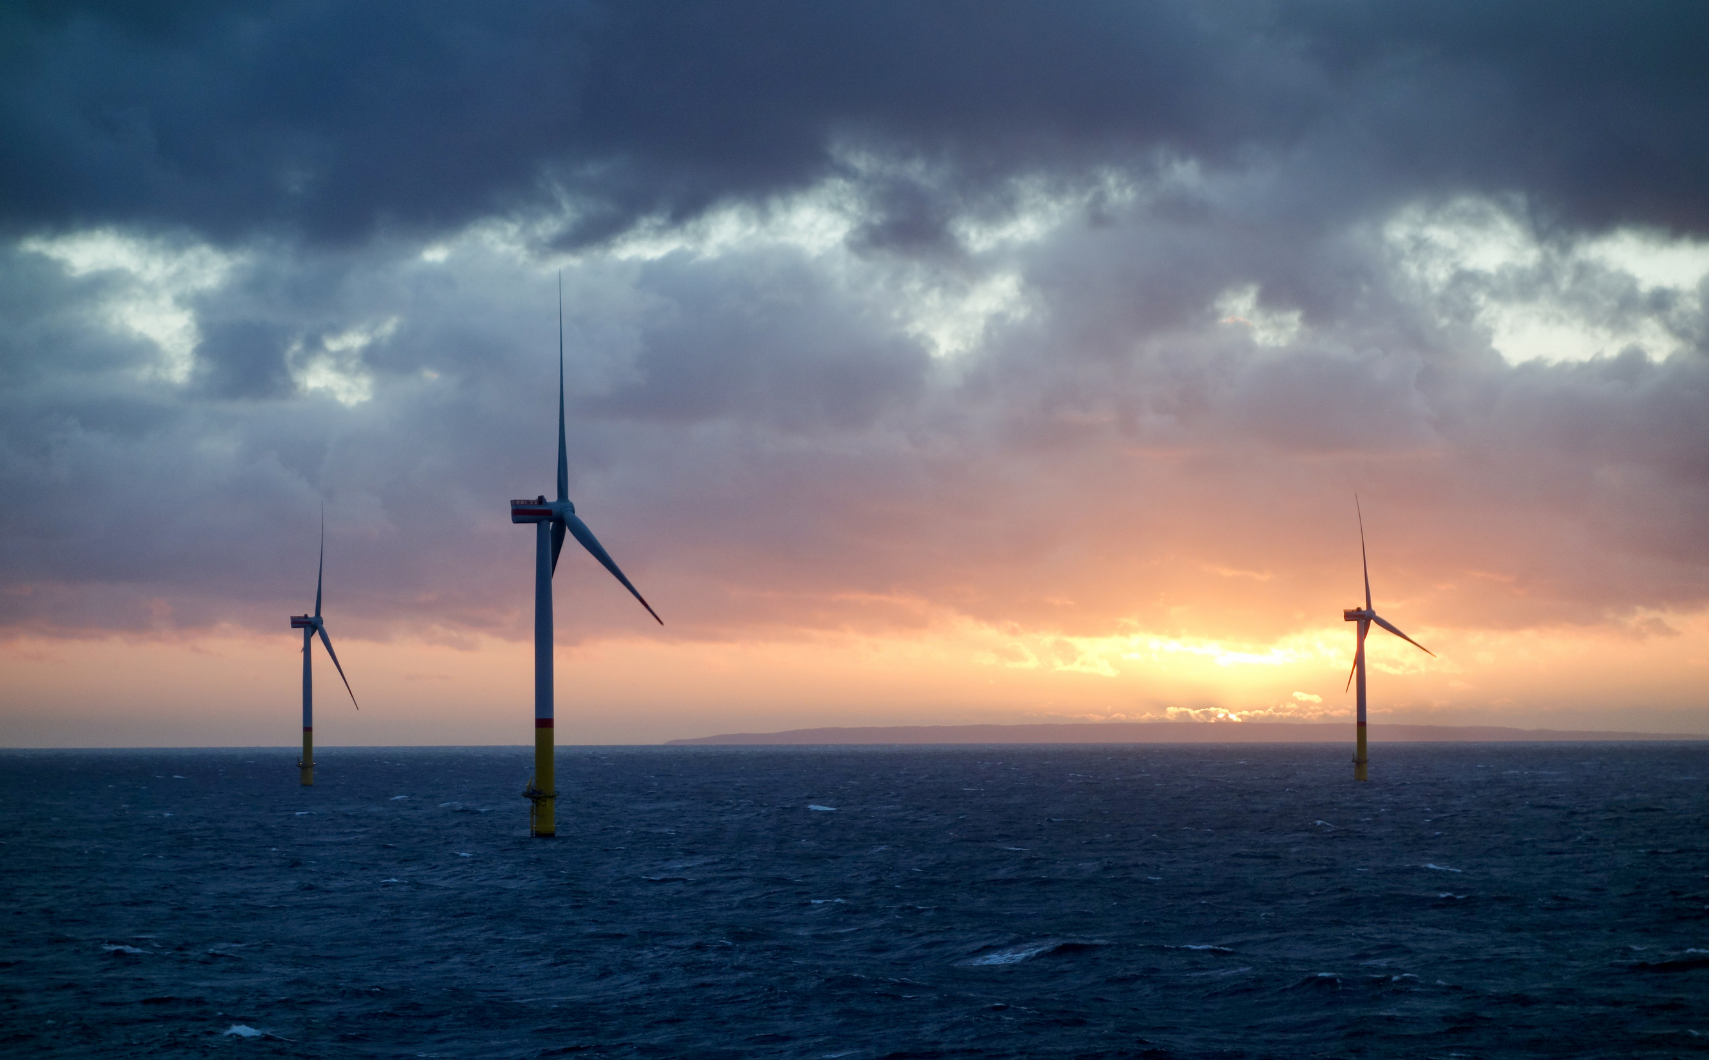
The next phase in the development of the renewable industry may just be about to occur. The Australian Energy Market Operator (AEMO) have been studying locations for new renewable developments. The majority of the market has been focusing on Renewable Energy Zones (REZ) on land but the solution maybe further off ashore. AEMO have located four offshore wind zones off the coast of NSW, Victoria, and Tasmania. The potential opportunities could add up to 40GW into the grid. To keep transmission costs down, AEMO have found locations close to land where significant ports are established that will allow the renewable output for the wind farms to be used at renewable hydrogen export hubs.

This year, AEMO updated its inputs into the Integrated System Plan and one of the significant changes from previous years is the volume of offshore wind availability. The 40GW identified is likely to be constructed over the next 20 years. At this stage the only offshore wind farm is the Star of the South wind farm located off the coast of Victoria and is likely to be 2,200MW. The Start of the South project is likely to connect into the grid via the Latrobe Valley and will feed in electricity as the coal fired generation in that region retires.

As the Hydrogen market also grows, offshore wind developers will focus on sites adjacent to the proposed hydrogen export facilities around Newcastle.

Offshore wind developers are concerned the legislation hurdles may stall the industry, so they are looking for support from governments to allow the industry to grow.

Oceanex Energy is looking to develop and construct up to 4 offshore windfarms off the coast of NSW with output likely to be over 7,000MW.

Oceanex Energy CEO Andy Evans says the clarity over the legislation is important given that project developers would likely need to spend up to $200 million to get a project to financial close.

He said it was an industry that would be likely dominated by major energy players – such as RWE, Iberdrola, Macquarie, and Equinox, along with big oil companies such as Shell and BP that are also expanding into offshore wind.

HYDROGEN PLANT CRITICAL

Andrew Forrest is one step closer to building a hydrogen fuelled power plant in NSW with the project being declared as a critical state significant infrastructure (CSSI) project. The CSSI status granted by the NSW Department of Planning, Industry and Environment show the $1.3B project has government support.

The duel fuelled 635MW power station is also hoping for support through the federal government’s Underwriting New Generation Investments scheme but at this stage no funding has been released to any project. The power plant forms just one part of Andrew Forrest’s plans for Port Kembla with his company Squadron Energy also developing the LNG import terminal.

The duel fuelled power station is designed to run on 50% green hydrogen but is likely to utilise the LNG available close by.

The Port Kembla power station is aiming for financial close by August 2022 and operational by Q125.

NSW Deputy Premier John Barilaro said the move to grant the project “critical state significant infrastructure” was driven by its “game changer” status in terms of supporting new renewable energy in NSW as coal power plants close.

The timing of this announcement is also good news for renewable energy project developers who have recently been invited to an expression of interest for the New England Renewable Energy Zone (REZ). The synchronous power station will not only provide an opportunity to burn clean green hydrogen but also provide much needed system strength services such as inertia.

The government has received 34GW of renewable energy interest which is 4 times the proposed capacity of the REZ. This has raised concerns from communities that fear over development of the area.

Matt Macarthur Onslow, from the Responsible Energy Development for New England, said the major expansion envisaged lacked “social licence”, and major divisions within local communities regarding renewables and concerns that they feel are being overlooked.

MORE WRITE DOWNS

In a sign that not only coal fired generators are impacted by changes in energy industry, last Friday more bad news came out the Australian Stock Exchange with Genex Power announcing a $16.5M write down on the value of its recently completed Jemalong solar farm due to dropping power prices.

In its FY21 results presentation, Genex Power outlined its revenue was underpinned by long term contracts for its operating assets and its projects in construct.

The Jemalong solar farm was completed on time and on budget so any losses could not be directed at this. The project located in western NSW was bought from solar developer Vast Solar.

The Jemalong assets were commissioned in July and are operating ahead of expectations however its recognition of the merchant revenue from the project in a falling market has caused value to be written down.

Despite the forecast for falling electricity prices, Genex is powering ahead with other developments including the Kidston Pumped Storage Hydro plant that will sit alongside the existing 50MW Kidston Solar farm that is planned to expand by a further 270MW in the future.

Genex is banking on the 250MW Kidston pumped hydro storage facility providing an arbitrage opportunity for the company as it can charge its storage by filling the upper reservoir during low day time prices and generate up to 250MW over the higher price parts of the day most likely the morning and evening peaks. If all modelling goes to plan Genex may also add up to 150MW of wind at the Kidston energy hub by 2025.

The company is also looking to diversify its portfolio geographically by installing a 50MW/100MWh battery at  Bouldercombe, in Queensland. The battery is likely to be operational by 2023 with the 250MW Kidston pumped hydro storage facility likely to generate by 2024.